 The Duck Curve
ARRAY and Shoals agree to merge; Shoals holders to own about 65%
Shoals CEO Brandon Moss would run the combined tracker and electrical balance-of-system maker, which the companies size at a preliminary, indicative $2.2 billion to $2.4 billion of pro forma 2027 revenue.
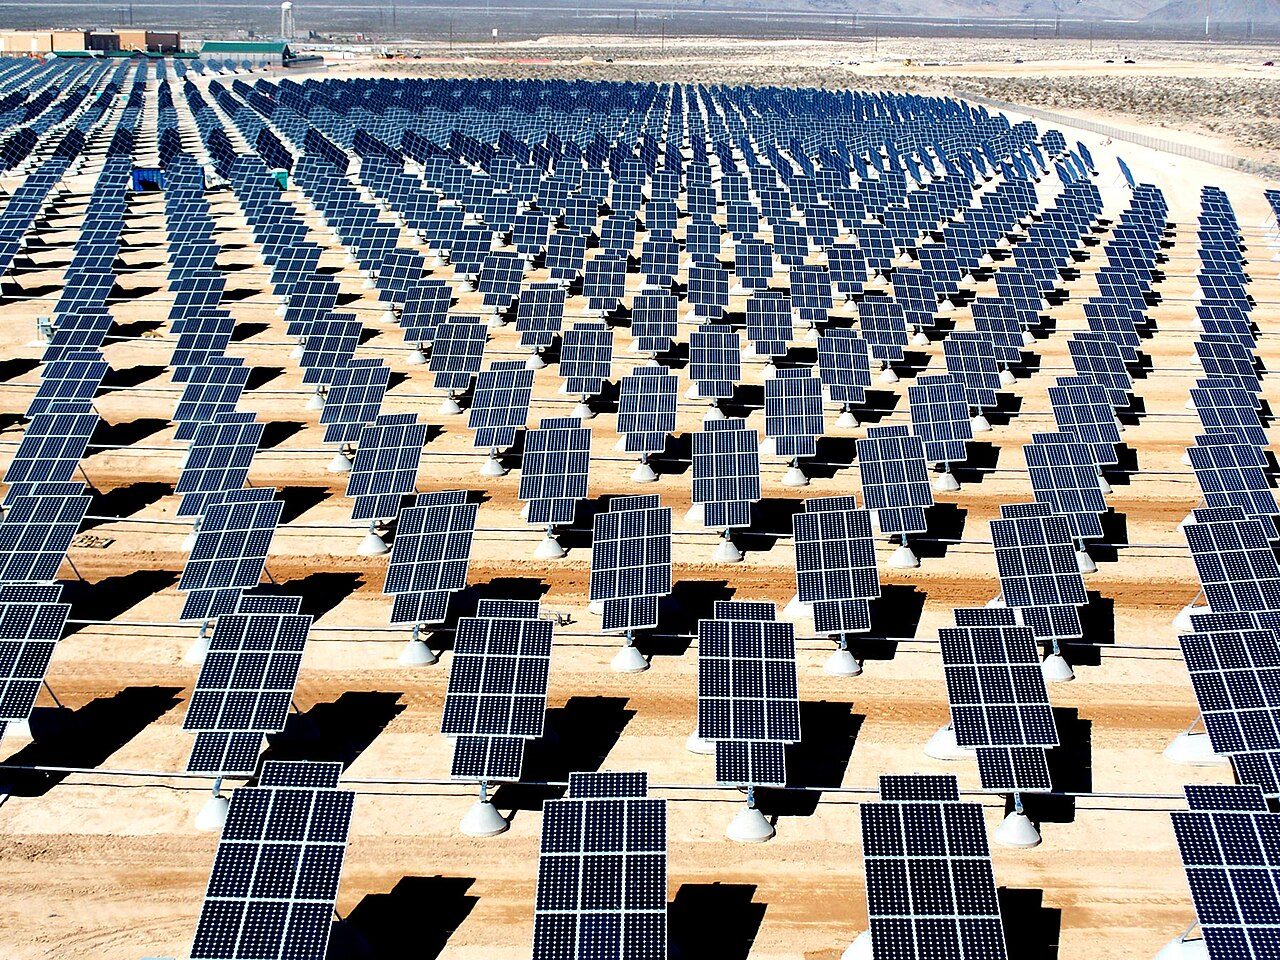
ARRAY Technologies and Shoals Technologies Group agreed on November 4, 2026 to combine in a stock-for-stock merger that puts a maker of solar trackers and racking and a maker of electrical balance-of-system (EBOS) equipment into one company. Shoals shareholders will receive 1.6931 ARRAY shares for each Shoals share and are expected to own about 65% of the combined company's basic shares, the companies' joint release says. ARRAY is the legal acquirer, and the companies expect to close in the first quarter of 2027.
On paper ARRAY is buying Shoals. The people and the shares point the other way: Brandon Moss, Shoals' chief executive, will run the combined company, Shoals' holders will own the larger stake, and ARRAY's chief executive, Kevin Hostetler, becomes a special advisor. ARRAY stays the corporate parent, and the headquarters will be in Albuquerque, New Mexico, with corporate offices in Chandler, Arizona, per ARRAY's 8-K. The chairman needs no introduction to either side. Brad Forth already chairs both boards, will chair the combined one, and took no part in either board's consideration of or vote on the deal. The rest of the ten-member board will be four independent directors from each company plus Moss.
Structure and wiring on one order
ARRAY sells trackers, fixed-tilt systems and foundations to utility-scale and distributed solar builders. Shoals makes electrical infrastructure for utility-scale solar, battery storage and data center power systems. "Although structural and electrical systems must operate seamlessly together in the field, they have historically been designed and sourced through separate channels," Hostetler said in the release. "This combination changes that."
The cross-selling pitch rests on one number. Only about 20% of projects the two companies served from January 2025 to September 2026 used products from both, the release says, a figure that assumes ARRAY owned its APA and AWM acquisitions over the whole period. The companies expect year-one synergies of about $15 million of run-rate adjusted EBITDA from cross-selling and about $20 million from cost savings, rising to more than $100 million a year within three years of closing.
They also put a size on the result: preliminary, indicative pro forma 2027 revenue of $2.2 billion to $2.4 billion and adjusted EBITDA of $410 million to $480 million, including expected year-one synergies. The footnote under those ranges says they "are provided solely to show the potential scale of the combined company and do not represent financial projections of either Shoals or Array." The companies estimate pro forma net debt of $873.3 million at the end of 2026, 2.6 times adjusted EBITDA, falling below 2 times by the end of 2027.
The preferred stock gets paid first
ARRAY's Series A preferred stock is part of the price. Under a letter agreement with Blackstone funds and VP Helios, ARRAY will redeem $161.3 million of it at 93% of the liquidation preference within 90 days after closing, an aggregate redemption price of $150 million plus accrued dividends in ARRAY's 8-K. Another $156.3 million goes at 96% in up to three installments of at least $52 million each, by the first, second and third anniversaries of that first redemption. Blackstone or VP Helios also gets a closing fee of 1.00% of the preferred's outstanding liquidation preference (plus unpaid dividends, in ARRAY's telling), and Shoals' 8-K adds that the preferred's cash dividend rate rises by 300 basis points on the fifth anniversary of closing, on top of increases already scheduled. In return, Blackstone and VP Helios agreed not to assert that the merger is a "Fundamental Change" under the preferred's terms. The release says the redemptions are expected to cut cash distributions by nearly $100 million over the next five years.
Shoals brings tax attributes as well: about $1.6 billion of tax amortization and $237 million of net operating losses, as of September 30, 2026. The combined company does not expect to pay a material amount of cash taxes in 2027, the release says.
Closing needs, among other conditions, both companies' shareholder votes, the end of the Hart-Scott-Rodino antitrust waiting period, an effective S-4 registration statement and Nasdaq listing of the new shares. Either side can walk if the deal has not closed by May 4, 2027, a date that extends automatically to November 4, 2027 if only the antitrust and Nasdaq conditions remain. The companies expect to file proxy materials with more financial detail by the end of 2026, and to agree on a new name and ticker before closing.
The break fees come with an inconsistency. Under the merger agreement, Shoals owes ARRAY $40.3 million if, among other triggers, Shoals' board changes its recommendation, and ARRAY owes Shoals $22.2 million in the mirror case; Shoals' 8-K says the same. ARRAY's own 8-K summary has the two fees the other way round.
Trackers that come with wiring
Tracker makers have been moving this way for a while. Nextracker, which also makes solar trackers, launched an EBOS business in May 2025 by buying Bentek in an all-cash deal of about $78 million including future earnout, with founder and CEO Dan Shugar saying "we are evolving Nextracker from a pure-play tracker supplier to a solar power platform company," per its results release. ARRAY had started down the same road on its own: its third-quarter release reports the completed purchase of Affordable Wire Management, which took it into wire management and into battery storage and data center markets, and a record $2.6 billion of executed contracts and awarded orders at September 30, 2026.
Battery storage heads the merger release's list of growth adjacencies, ahead of data center infrastructure. More than 16% of the utility-scale solar capacity added in the US in 2026 through September sits beside operable batteries, per the Energy Information Administration, and Shoals already sells EBOS for battery storage.
Outlook
If the antitrust waiting period and the two shareholder votes go through on the companies' schedule, the combined company would sell trackers and EBOS through one design package against Nextracker, which has offered both since its Bentek deal. The synergy targets are company expectations, and the 2027 ranges are, by the release's own footnote, not projections of either company; the proxy materials due by the end of 2026 are where more detailed financials should first appear.
⚠ The Outlook extrapolates from the companies' stated closing conditions and timetable, their synergy expectations and footnoted 2027 ranges in the November 4, 2026 release, and Nextracker's May 2025 Bentek acquisition release.
Sources
Primary
- ARRAY Technologies and Shoals Technologies Group Announce Transformative Merger, Creating an Integrated Energy Infrastructure Platform (joint press release, Exhibit 99.1 to Shoals Form 8-K) · Shoals Technologies Group and ARRAY Technologies (SEC EDGAR)
Supporting
- Nextracker Reports Q4 and FY25 Financial Results; Launches eBOS Business With Acquisition of Bentek · Nextracker (SEC EDGAR)
- ARRAY Technologies, Inc. Form 8-K, November 4, 2026 (Items 1.01, 5.02, 7.01) · ARRAY Technologies (SEC EDGAR)
- Shoals Technologies Group, Inc. Form 8-K, November 4, 2026 (Items 1.01, 5.02, 7.01) · Shoals Technologies Group (SEC EDGAR)
- Agreement and Plan of Merger and Reorganization among ARRAY Technologies, Shoals Technologies Group and Pensacola Merger Sub (Exhibit 2.1) · ARRAY Technologies (SEC EDGAR)
- ARRAY Technologies Reports Financial Results for the Third Quarter 2026 (Exhibit 99.1) · ARRAY Technologies (SEC EDGAR)
Copies of cited sources are retained where available. If a link no longer resolves, request a copy at contact@theduckcurve.com.